You’ve missed a mortgage payment in Edmonton. Here’s the actual timeline
The short answer
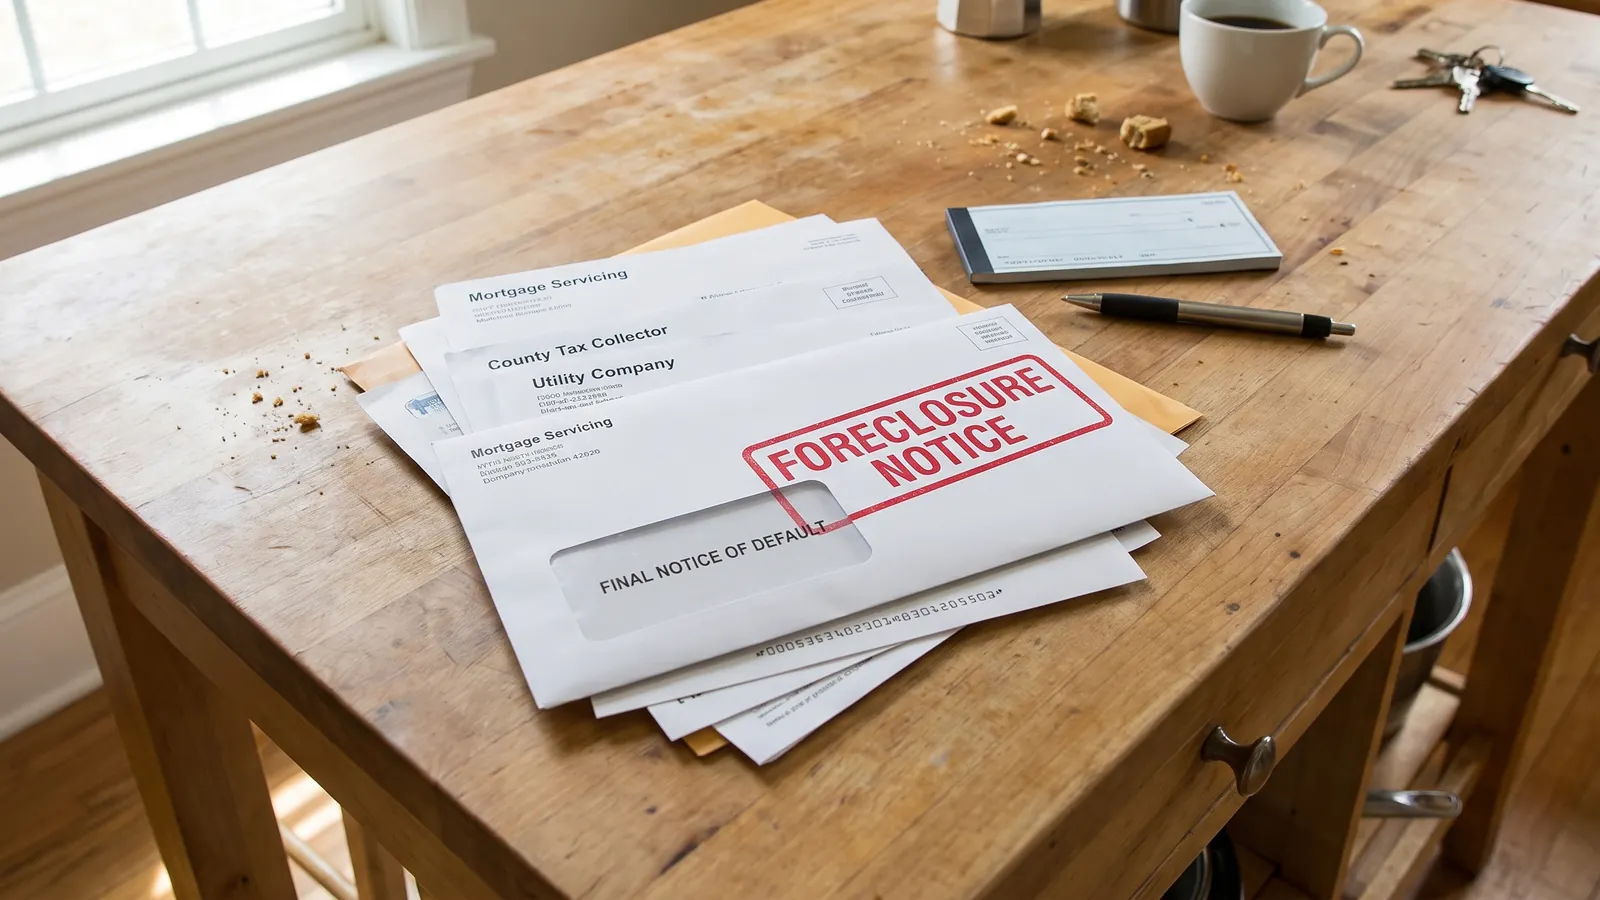
A missed mortgage payment is not a foreclosure. In Alberta your lender cannot sell your home by writing you a letter — it has to take you to court and get a judge's permission at every step. From court papers to a listing is two or three months at the very least, and often eight or nine.
Key takeaways
- Nothing has been taken from you yet: while you still own the home you can sell it, refinance it, or catch up the payments.
- Alberta is slower than Ontario or the United States because the lender has to go to court and get permission at every stage.
- There are six stages, and your options close one at a time rather than all at once.
- From court papers to a listing is two or three months at minimum and often eight or nine; these files commonly run past a year.
- Your clock starts when the court grants the order — the months you already spent behind do not count against you.
- Six months is the usual window for a home, but the court can shorten it, and it has granted as little as one day.
- Legal costs pile up against your home the whole time and come out of your money before you see any of it.
Nothing has been taken from you yet
A missed mortgage payment is not a foreclosure. In Alberta it is not close to one, and the distance between the two is measured in months rather than days.
That matters because the decisions that protect your money are all made early, and people who assume the house is already gone stop making them. So before anything else: the home is still yours. You can still sell it, refinance it, or catch up the payments, and while that is true you are the one deciding how this ends.
Alberta gives you more time than the internet says
Most of what you will read about foreclosure is American, or from Ontario. In Ontario a lender can sell your home after giving you notice. In parts of the United States it is faster still.
Alberta does not work that way. Your lender cannot sell your home by writing you a letter and hiring an agent. It has to take you to court, and it has to get a judge’s permission at every step. That is slow and expensive for the lender, and the time it buys is the most valuable thing you have right now.
What actually happens, and in what order
There are six stages. Knowing which one you are in tells you which choices are still available, because they close one at a time rather than all at once.
| Stage | What happens | What it means for you |
|---|---|---|
| 1. You fall behind | Payments are missed and the lender contacts you | Everything is still open, including simply catching up |
| 2. A lawyer’s letter | The lender’s lawyer writes demanding payment | Legal costs start being added to what you owe |
| 3. Court papers | The lender files a claim and you are served with it | You can still sell or refinance the home yourself |
| 4. The court sets a deadline | A judge grants the lender an order with a date on it | Your countdown starts here — not when you first fell behind |
| 5. Your window | The period the court gives you to pay off or sell | The last stage where you choose the agent and the price |
| 6. The sale leaves your hands | The home is listed under court order, or title goes to the lender | You no longer control what it sells for |
How long you realistically have
From the day court papers are filed to the day a property can be listed is two or three months at the very least, and often eight or nine. Add the months you were behind before that, and the window the court gives you afterwards, and these files commonly run past a year.
That is not permission to wait. Every month adds legal costs that get charged against your home and come out of your money before you see any of it — and the options that end with you keeping the house are the first ones to close.
The deadline that counts is not the one you think
It is not your first missed payment. Your clock starts when the court grants the order, and for a home the starting point is six months from that date. The months you have already spent behind do not count against you.
But six months is a default, not a promise. The court can shorten it or extend it, and in practice it has granted everything from one day to the full six months. What moves it is a short, fixed list — and it is worth reading as a checklist, because if you are going to ask for more time, this is what the judge is allowed to weigh:
… (i) the ability of the debtor to pay, (ii) the value of the land including the improvements made on it, (iii) whether the land has been abandoned, (iv) the nature, extent and value of the security held by the creditor, (v) the earning capacity of the debtor, and (vi) whether the debtor’s failure to pay was due to temporary or permanent unemployment or other conditions beyond the control of the debtor.
What that list means in practice
In plain terms: the court wants to know whether you can realistically pay, whether there is value in the home, whether you are still living in it and looking after it, and whether what went wrong was something that happened to you rather than something you chose.
So if you are asking for more time, bring the things that speak to that. A job offer with a start date. A layoff notice. Medical records, if illness is what did this. Evidence that the home is occupied and maintained. Nothing else on that list will help, and everything on it will.
What to do this week
Open the letters. A file where the homeowner has never responded is the easiest kind for a lender to push forward, and several of the routes that keep you in the home need the lender to agree to something.
Find out two numbers. What you actually owe — the balance, the arrears and the costs so far — and what the home would sell for today. Everything else follows from those two figures, and working out where the value sits and what it leaves you is exactly the part Ryan can help with. If the second number is comfortably bigger than the first, you have money in the house worth protecting and time to protect it. If it is not, this is a different conversation, and part of it belongs with a licensed insolvency trustee rather than a real estate agent.
Tell someone. This is the part people skip. The shame of it keeps more homes in foreclosure than the arrears do, and every week spent not saying it out loud is a week of options quietly closing.
The rest of this series
Start with the overview if you have not read it: Foreclosure in Edmonton: what to do when you’re behind on your mortgage. These four go deeper on one part of it each.
1. The timeline after a missed mortgage payment (you are here)
Ryan McCann
Ryan McCann is an Edmonton REALTOR® with over 23 years of experience helping more than 2,200 buyers and sellers. His work spans every Edmonton neighbourhood and property type, bringing deep local market knowledge and practical guidance to buying or selling a home in Edmonton.
He has worked on all sides of the foreclosure process, representing both sellers and buyers through the courts, and has a deep understanding of how it actually unfolds.
Contact Ryan today at 780-964-8445 to talk through your next step.
Reviewed 20 September 2026
Sources
Law of Property Act, RSA 2000, c L-7, ss. 39–45 (Alberta King’s Printer) — https://kings-printer.alberta.ca/documents/Acts/l07.pdf
J.F. Reich & D.M. Hendrix, “The Foreclosure Sale Process”, Legal Education Society of Alberta — https://www.lesaonline.org/samples/61836_07_p1.pdf
Foreclosure Fee and Disbursement Guideline – Alberta, Court of King’s Bench — https://albertacourts.ca/docs/default-source/qb/foreclosure_fee_and_disbursement_guidline_alberta_21082018.pdf
Centre for Public Legal Education Alberta — https://www.cplea.ca/
This article is information, not legal advice. For advice on your own situation speak to a lawyer; for debt that goes beyond the mortgage, speak to a licensed insolvency trustee.
Frequently asked questions
How many payments can I miss before I lose my house in Alberta?
There is no set number. Losing the home requires a court process, not an automatic trigger: your lender has to file in court and get an order before any sale can happen, and the court then gives you a window to pay off or sell. Missing a payment starts a conversation with your lender, not a countdown to eviction.
When does my six months actually start?
When the court grants the order — not when you first fell behind. Whatever months you have already spent in arrears do not come off it.
Can the court give me less than six months?
Yes. Six months is the usual starting point for a home, but the court can shorten or extend it, and in practice has granted anywhere from one day to the full six months. What it weighs is whether you can realistically pay, whether there is value in the home, whether you are still living in it and looking after it, and whether what went wrong was beyond your control.
What should I do first?
Open the letters, and find out two numbers: what you actually owe including arrears and costs, and what the home would sell for today. Everything else follows from those two figures. If the second is comfortably bigger than the first, you have money worth protecting and time to protect it.
Need help understanding your situation?
The most useful thing you can have right now is an honest number: what the home is worth today, and what would be left after the mortgage, the arrears and the costs. Ryan can help you understand where the value is and what your options are.
Talk to Ryan